

The Daily Dish
October 6, 2026
French Toast?
Fortune magazine weighed in on the misfortune that is French government finance:
Faced with the prospect of a far-right or a far-left president, the bond market doesn’t see France curbing its rapidly growing pile of debt anytime soon and has started weighing the possibility that the eurozone’s second largest economy could default. That’s according to Thierry Wizman, global FX and rates strategist at Macquarie Group. In a note Thursday, he said the cost of insurance against a French default is now the highest among the major EU countries and the U.K.
Nobody should be surprised. After all, the French government budget deficit is a whopping 5.4 percent of gross domestic product (GDP), and debt outstanding has reached 119 percent of GDP. And France is unlikely to grow its way out of the problem; GDP growth stagnated in the 2nd quarter and was only 0.7 percent year-over-year. In these circumstances, yields on 10-year bonds have surged north.
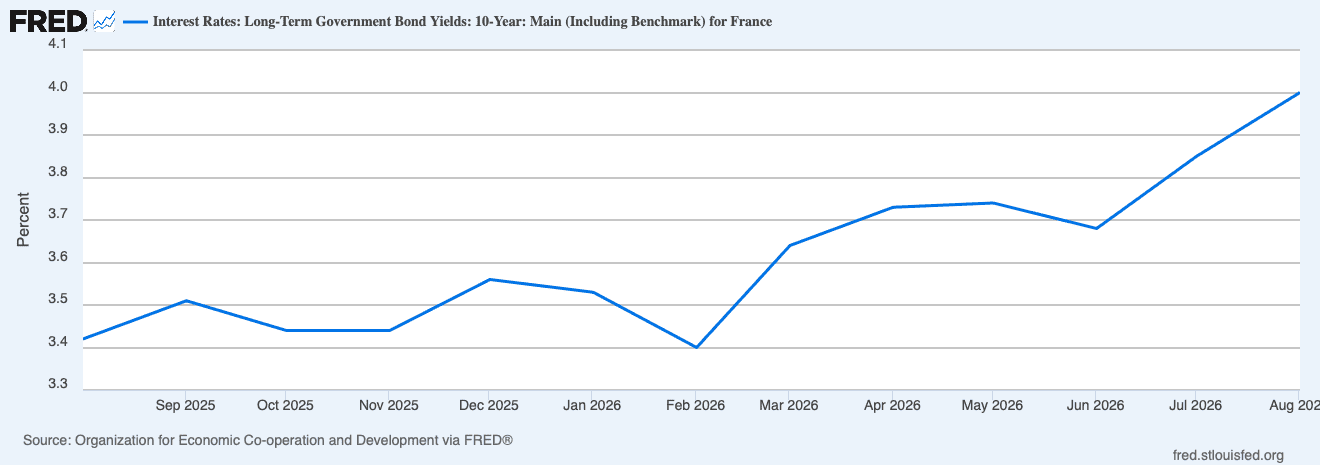
These numbers should be a cautionary tale for U.S. policymakers. The federal budget deficit is larger than in France, although the debt outstanding is closer to 100 percent of GDP. And the U.S. economy continues to grow much more rapidly. Interest consumes 7 percent of French revenue, but over 18 percent of receipts in the United States. Nevertheless, the run-up in the yields on 10-year Treasuries is even sharper and larger than in France.
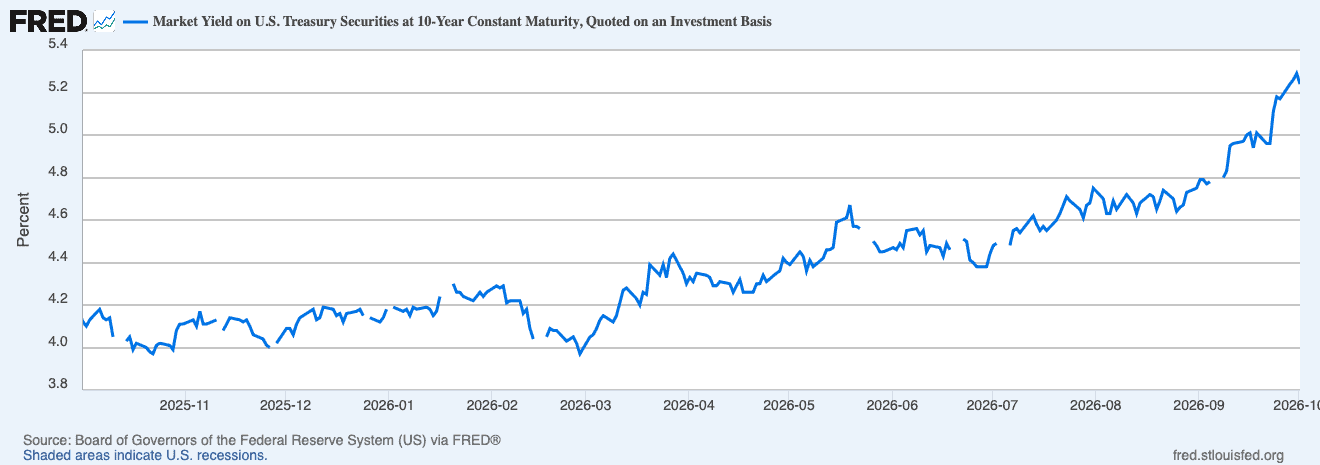
Nobody knows how long before the U.S. faces French-like bond market pressures. But there is no particularly compelling reason to find out – and no time like the present to begin to rein in deficits and control debt.
Fact of the Day
As of September 30, the Fed’s assets stood at $6.7 trillion, down $5 billion from the prior week but more than $156 billion higher than a year ago.