

The Daily Dish
October 13, 2026
Inflation Outlook
Tomorrow the Bureau of Labor Statistics will release the September report on the Consumer Price Index (CPI), which will be an important input into the decisions of the Federal Open Market Committee at its October meeting. What can we expect? Most of the recent moves in top-line inflation have been driven by changes in global oil prices, in particular, and energy prices, in general.
From some other perspectives, the recent trend is favorable. Core inflation strips out the volatile food and energy components. Year-over-year core inflation was 2.9 percent in May, but fell to 2.6 percent, 2.5 percent, and 2.4 percent in June, July, and August, respectively. That suggests a steady movement toward the 2.0 percent target.
Unfortunately, the softening core inflation reflects some anomalous movements in shelter inflation (see chart below). Shelter, recall, accounts for roughly one-third of the CPI. For a long time, shelter inflation was the bane of the Fed’s existence, averaging 6.2 percent between 2022 and 2024. Success in lowering shelter inflation was imperative to reaching the 2.0-percent target inflation. From that perspective, the 1.1-percent (annual rate) shelter inflation in June and 1.2 percent in July is good news. But that June decline was driven by soft hotel and lodging prices, while the July number is less obvious to explain.
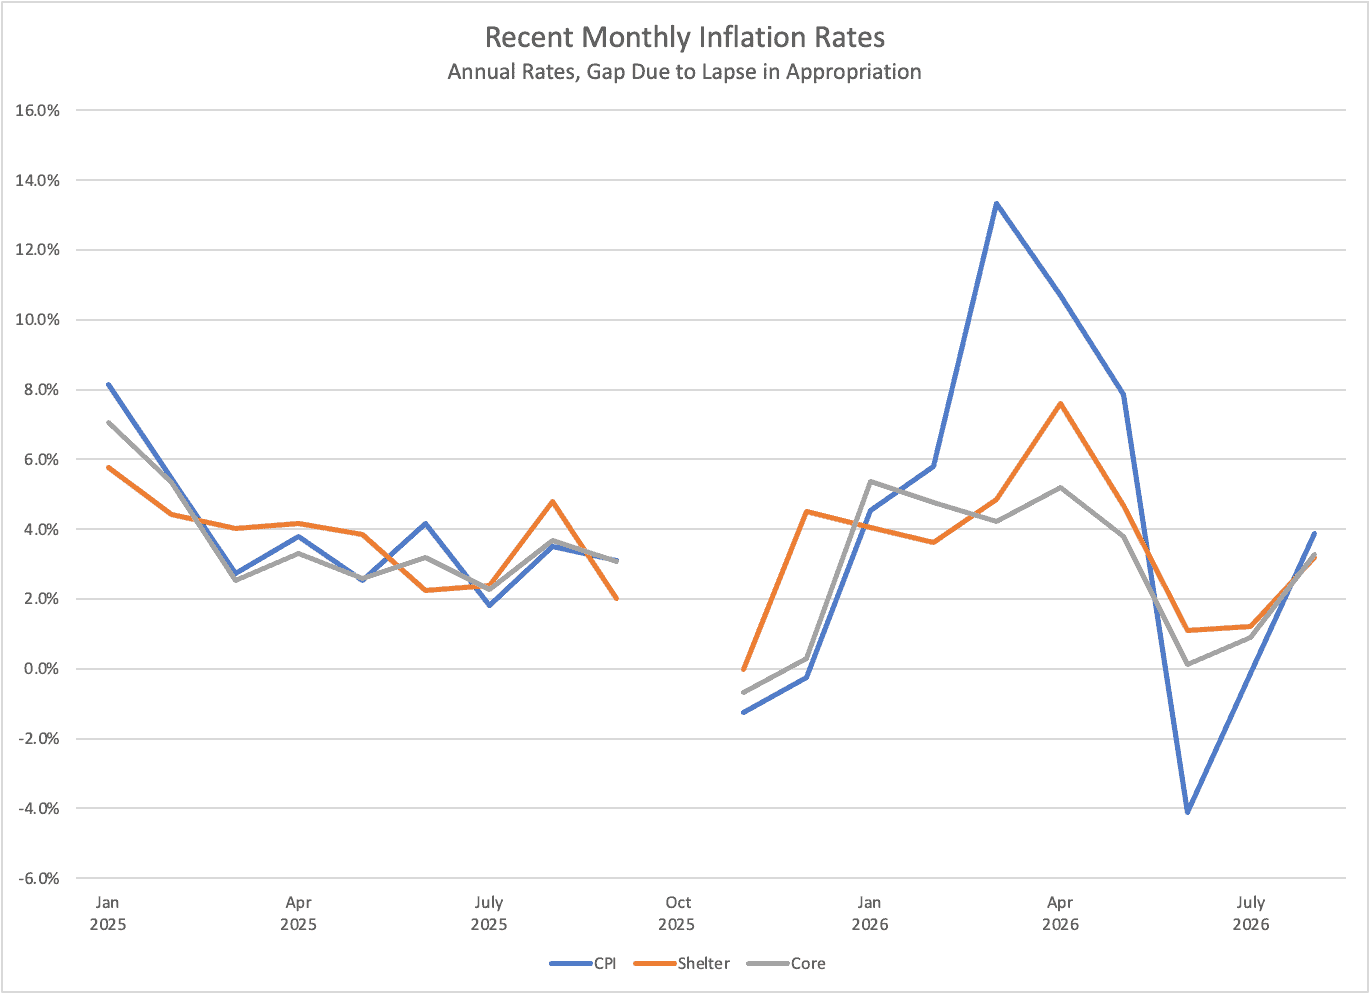
Shelter inflation regrettably rebounded to 3.2 percent in August. What will it turn out to be in September? More generally, will the report bring stiffer core inflation, thereby interrupting the descent toward 2.0 percent?
Fact of the Day
In fiscal year 2026, federal agencies published approximately $1.5 trillion in self-reported regulatory cost reductions under the Trump Administration’s updated regulatory budget program.